
What Does an Ultra-Large Excavator Really Cost Over Its Service Life?
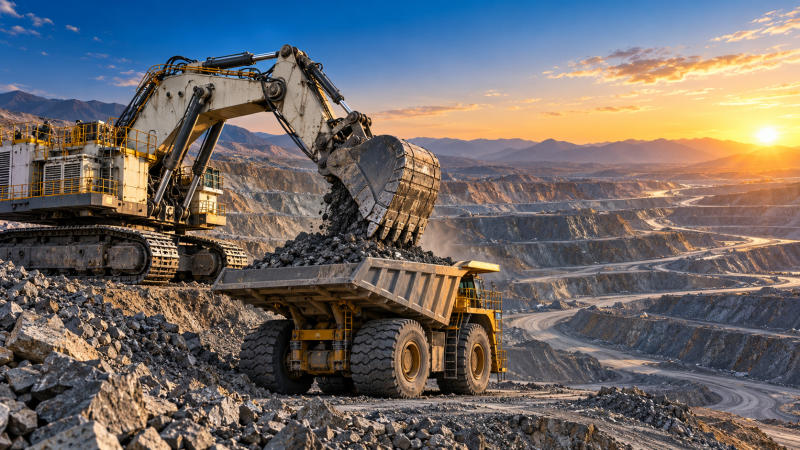
The purchase price of an ultra-large excavator is only the opening number in a much larger capital commitment. A machine in the 400-tonne-and-above class can remain on a mine balance sheet for many years, but its economic outcome is determined less by the invoice value than by the cost of keeping it available, productive, safe, and supportable through repeated high-load duty cycles.
The central question is not “What does the excavator cost?” but “What does each productive tonne moved cost after ownership, energy, maintenance, downtime, financing, and end-of-life value are included?” Two machines with similar bucket capacities can produce sharply different lifecycle economics because they operate in different material, climates, shift patterns, fuel regimes, maintenance systems, and haulage matches. A credible approval should therefore treat the machine as a production asset embedded in a mining system, not as an isolated equipment purchase.
The lifecycle cost equation is wider than the equipment quotation
A useful total cost of ownership model starts with five cost pools:
- Initial capital deployed, including the machine, attachments, commissioning, freight, assembly, taxes where applicable, and site preparation.
- Cost of capital, including interest, lease charges, currency exposure, and the cash tied up in strategic spare parts.
- Operating cost, led by diesel or electricity, lubricants, ground-engaging tools, operators, and consumables.
- Maintenance and repair cost, including planned service, component rebuilds, unscheduled repairs, field labour, tooling, and logistics.
- Value recovery, including resale potential, trade-in value, recoverable components, and the cost of demobilization or disposal.
For approval purposes, the basic calculation can be expressed as:
Lifecycle cost = acquisition and deployment + financing + operating cost + maintenance and repair + downtime losses + end-of-life obligations − residual value.
The formula is simple; the quality of the decision depends on the assumptions underneath it. Fuel consumption cannot be evaluated as a catalogue figure. Maintenance cannot be represented by a flat percentage of purchase price. Residual value cannot be assumed from a smaller excavator market where resale channels are broader. In ultra-large excavators, each assumption must be tied to the intended production environment.
Acquisition cost begins before the machine reaches the mine
The base machine quotation can be substantial, but it is often incomplete as an investment figure. Ultra-large excavators may require special transport planning, port handling, oversized-load permits, site assembly support, lifting equipment, commissioning technicians, and a substantial initial parts package. Remote mines can add considerable cost through long-distance logistics, limited road access, restricted seasonal transport windows, or the need to mobilize specialized assembly crews.
Attachment configuration also changes the true capital requirement. A backhoe configuration and a front-shovel configuration are not interchangeable commercial choices. They support different loading patterns, bench conditions, truck fleets, and digging methods. The selected boom, stick, bucket, tooth system, wear package, track shoe width, cold-weather provisions, fire-suppression equipment, and telematics package can all affect both initial cost and later operating economics.
A low initial package can be financially misleading if it excludes the components required for reliable operation in abrasive ore, hard digging, high altitude, extreme heat, or severe cold. Conversely, specifying every available option without a duty-cycle rationale can lock unnecessary capital into the project. The approval case should distinguish between compliance-critical, productivity-critical, and convenience-oriented items.
Energy cost is a production-variable problem, not a fuel-price line item
In conventional diesel hydraulic excavators, fuel is among the most visible lifecycle expenses, but its effect depends on utilization and load factor. An excavator operating continuously in hard, fragmented rock will not consume fuel in the same way as one loading softer overburden. Idle time, swing angle, face height, bucket fill factor, truck spotting discipline, operator practice, and hydraulic system condition all influence energy used per tonne.
The relevant metric is therefore not simply litres per hour. It is better assessed through fuel per productive hour and, where reliable production measurement exists, fuel per tonne moved. A machine with a higher hourly burn may still have lower energy cost per tonne if it achieves materially higher payloads, better bucket fill, fewer passes per truck, or more stable cycle times. The reverse is also true: an oversized excavator assigned to an undersized truck fleet can consume energy while waiting, reducing the economic value of its capacity.
Electrically powered excavators change the cost structure rather than eliminate energy risk. Their economics depend on the price and reliability of site power, cable management, substation capacity, electrical infrastructure, planned mine progression, and the consequences of power interruptions. The capital needed to establish a reliable electrical supply must be considered alongside the machine itself. Where the operating profile is stable and power is dependable, electric drive can offer a different long-term energy and maintenance profile; where mining faces move frequently or power availability is constrained, the operational trade-off may be less favorable.
Maintenance is dominated by wear, rebuild strategy, and service access
Ultra-large excavators are engineered for sustained production, but high production does not mean low maintenance exposure. The most consequential costs are often concentrated in a limited set of high-value systems: engines or electric drive components, hydraulic pumps and motors, cylinders, swing systems, travel drives, structures, undercarriage assemblies, and large buckets with their wear protection.
Maintenance budgets become unreliable when they treat all hours as equal. A productive hour in low-abrasion overburden and a productive hour in hard, abrasive material impose very different stresses on buckets, teeth, shrouds, pins, bushings, cylinder rods, pumps, and structural components. High-impact digging can accelerate fatigue and wear even if the recorded operating hours appear normal.
Component rebuilds deserve separate treatment from routine maintenance. A planned rebuild may be financially rational when carried out before secondary damage spreads through associated systems. Deferring it to protect a short-term operating budget can create a larger failure event, longer downtime, emergency freight charges, and lost production. The appropriate question is not whether a rebuild is expensive; it is whether the machine can continue operating economically without it.
Service access also affects the maintenance cost curve. A supplier’s quoted parts price is only one element. Lead times, regional inventory, field-service coverage, diagnostic capability, availability of trained technicians, exchange-component programs, and the ability to source critical parts under customs or cross-border constraints all influence both repair cost and availability. In a remote mine, a relatively modest failed component can create a disproportionately expensive event if it immobilizes the excavator while parts and specialist labour are mobilized.
Downtime has to be priced as lost system output
Many ownership models understate downtime because they record only repair invoices. That approach misses the larger economic effect: a stopped excavator may interrupt truck loading, reduce crusher feed, disrupt shift plans, create queueing in the haul fleet, and force less efficient deployment of alternative equipment.
The cost of downtime should not be estimated from the excavator’s hourly ownership cost alone. It should reflect the contribution margin of the mining system affected by the lost loading capacity. This requires a realistic view of redundancy. If another excavator can absorb the work without materially changing mine output, the production loss may be limited. If the machine is the primary loader at a constrained face, the cost can be much higher than the maintenance invoice suggests.
Availability guarantees should be read carefully. A contractual availability percentage can be valuable, but its definition matters. It may exclude certain events, depend on scheduled maintenance windows, require specific operating practices, or provide remedies that do not fully offset lost mine output. Financial approval should examine the calculation method, exclusions, response-time commitments, parts obligations, and the practical enforceability of remedies in the relevant jurisdiction.
Productivity must be measured at the loading system level
An ultra-large excavator creates value only when its capacity matches the rest of the operation. Bucket size, digging force, crowd force, cycle time, payload accuracy, and truck pass match all matter. A machine capable of loading a haul truck in fewer passes can reduce cycle variability and improve fleet utilization, but only if the bucket payload remains within truck limits and material conditions allow consistent filling.
Mismatch is a common source of hidden cost. A very large excavator paired with too few trucks may spend productive time waiting. A bucket that is too large for the truck body can create payload variation, spillage, structural loading concerns, or inefficient partial passes. A machine selected mainly for peak capacity may also prove uneconomic if the mine plan does not provide enough continuous loading work to use that capacity.
The business case should therefore model tonnes moved rather than machine hours alone. Productive tonnes should be adjusted for expected utilization, planned maintenance, operating delays, material variation, truck availability, shift-change losses, and weather or site restrictions where relevant. Nameplate capacity is useful for comparison, but it is not an operating forecast.
Financing, currency, and working capital can alter the ranking of bids
For cross-border equipment purchases, the apparent lowest-cost offer may not be the lowest financial commitment. Payment milestones can require large cash outflows well before commissioning. Import duties, local taxes, inland transport, insurance, letters of credit, foreign-exchange movements, and financing terms can materially alter the present value of the investment.
Spare-parts strategy also has a working-capital consequence. Holding critical pumps, motors, cylinders, electronic modules, and wear inventory on site improves resilience but ties up cash. Relying entirely on supplier delivery reduces inventory value on the books but increases exposure to lead time, transport disruption, and unplanned downtime. The correct inventory level depends on failure criticality, lead time, component value, and the mine’s ability to tolerate a stoppage.
A consistent comparison should convert all bids into a common currency, common delivery basis, common financing assumption, and common operating horizon. It should also identify which risks remain with the supplier and which remain with the buyer. A lower quoted price that transfers logistics, commissioning, warranty administration, and parts availability risk to the owner is not necessarily a lower-cost offer.
Residual value is real, but should not rescue a weak operating case
Residual value is often less predictable for ultra-large excavators than for broadly traded construction equipment. The buyer pool is narrower, transport is complex, machine condition is heavily site-dependent, and the resale value of a particular configuration may depend on demand in specific mining regions. A well-documented maintenance history, remaining component life, rebuild records, emissions configuration, structural condition, and available dealer support can all influence value recovery.
Residual value should be treated conservatively in approval models. It is reasonable to recognize recoverable value from a maintained, supportable asset, but the investment should remain viable without relying on an aggressive resale assumption. Component recoverability can also matter: a machine near the end of its primary mine assignment may retain value through rebuilt components, attachments, or transfer to a lower-intensity operation. Those outcomes are possible, not guaranteed.
What a credible approval model should challenge
The strongest investment cases make their assumptions visible. They do not merely present a single lifecycle total. They show how the result changes when fuel or power cost rises, annual operating hours fall, bucket wear accelerates, a major component rebuild occurs earlier, truck availability declines, or residual value is weaker than expected.
Particular attention should be given to the assumptions that can reverse the decision:
- Expected productive hours per year rather than scheduled hours.
- Tonnes moved per productive hour under the actual material and bench conditions.
- Fuel or electricity use per tonne, not only per hour.
- Planned component rebuild timing and cost, including labour and downtime.
- Critical spare-parts lead times and the inventory required to manage them.
- Truck-excavator matching and the cost of idle loading capacity.
- Downtime assumptions linked to mine-system output, not just repair expenditure.
- Currency, financing, freight, commissioning, and import-related exposure.
- Residual value under a conservative disposal or resale scenario.
The most defensible answer to ultra-large excavators cost is therefore a range of lifecycle outcomes under defined operating conditions, not one headline number. The machine may justify its capital intensity when it delivers stable high-volume loading, fits the truck fleet and mine plan, has credible parts and service support, and retains sufficient availability through planned rebuilds. It becomes financially fragile when utilization is uncertain, production is constrained elsewhere in the system, energy assumptions are optimistic, or maintenance support is treated as an afterthought.
Approval should rest on the cost per productive tonne and the risk surrounding that number. Purchase price remains important, but it is rarely the variable that determines whether an ultra-large excavator creates value over its service life.
Related News
 Sep 30, 2026What Does an Ultra-Large Excavator Really Cost Over Its Service Life?Ultra-large excavators cost far more than purchase price. Explore lifecycle expenses, uptime risks, energy use, maintenance, and cost-per-tonne insights.
 Sep 29, 2026Infrastructure Construction Standards: A Project Manager’s Guide to ComplianceInfrastructure construction standards guide for project managers: turn requirements into field controls, hold points, traceability, and compliant delivery.
 Sep 28, 2026How to Specify Custom Mining Equipment for Abrasive Ground and High-Load HaulageCustom mining equipment for abrasive ground and high-load haulage: learn how to optimize payload, wear protection, powertrains, uptime, and lifecycle cost for safer, reliable production.
 Sep 30, 2026When does a lower construction machinery price raise lifecycle costs?Construction machinery pricing can hide costly risks. Discover how downtime, fuel use, maintenance, productivity, and resale value shape total lifecycle costs.
Ms. Elena Rodriguez
Weekly Insights
Stay ahead with our curated technology reports delivered every Monday.